
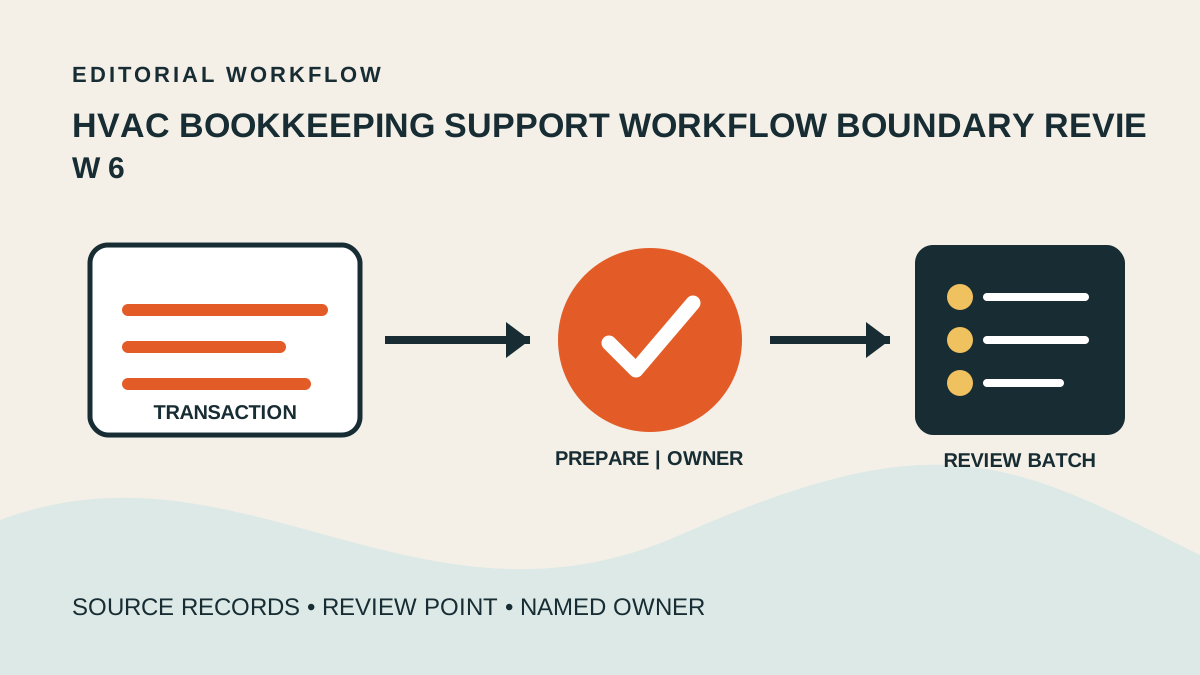
Conceptual, non-empirical finding
Workflow boundary review: This conceptual review asks where repeatable preparation ends and accountable judgment begins.
For hvac bookkeeping support, this is a study design and operating interpretation. It reports no measured result, person, business outcome, or performance claim.
Actual workflow records
Inspect records created by the operating workflow rather than hypothetical examples. For this service, the relevant record path is: Collect invoice and receipt records from approved sources and check that each transaction has a legible document and reference. Match customer payments and supplier charges to existing records without creating an unsupported match or classification. Prepare the transaction using documented bookkeeping rules and attach the source evidence for reviewer inspection. Place duplicates, variances, credits, refunds, tax questions, new vendors, and unclear job allocations in the financial review queue. Record the approved outcome and preserve a reconciliation trail without deleting the original discrepancy.
The review set should retain the inputs used by the role. Provide least-privilege access to approved invoice, receipt, payment, vendor, job-cost, and bank-feed records plus the current chart-of-accounts guidance from the financial owner. Each transaction should retain its source document, date, amount, counterparty, job or business-purpose reference, payment status, and reviewer when financial judgment is required.
Sample and comparison method
Select actual workflow records from one defined queue and period. Include ordinary records and records returned for review rather than choosing only clean examples.
Compare each recorded action with the written role boundary, required source fields, approval point, and named owner. Record ambiguity as a design question, not as staff performance evidence.
Evidence to inspect
A review-ready transaction batch with linked invoice or receipt evidence, documented preliminary classification, job reference, and reviewer flags.
A reconciliation exception schedule listing unmatched payments, duplicate-looking charges, amount or date variances, vendor gaps, and the financial owner needed.
Check transaction amount, date, counterparty, document identifier, and job reference against the source before placing it in the bookkeeping review batch.
Use duplicate checks and preserve an audit trail for every reconciliation change; reviewer approval must remain visible for classification or correction decisions.
Exceptions and escalation
Pause a transaction when support is missing, amounts conflict, a bank item is unfamiliar, vendor details changed, a customer payment is split, or the job reference is uncertain.
Escalate suspected fraud, payroll items, tax treatment, chargebacks, refunds, write-offs, account changes, cash movements, and material reconciliation differences to the authorized financial owner.
Bounded interpretation
The review can expose places where ownership or instructions need clarification. It cannot establish productivity, causation, compliance, or performance across the business.
The support role may organize documents and prepare bookkeeping records; it may not authorize payment, move funds, approve vendors, decide tax treatment, sign filings, issue refunds, or make final account classifications.
Financial approval, accounting policy, payroll, tax, banking access, journal-entry approval, and final reconciliation remain with qualified authorized personnel.
Map the next controlled handoff
Bring one recurring workflow, its source records, and the person who owns exceptions.
Plan a free consultation